Director Compensation in Japan: When Can You Change It?
【Koshida Accounting Firm Column Date:】
Many foreign business owners are surprised to learn that changing director compensation during the fiscal year can create unexpected tax problems in Japan.
In many cases, increasing or decreasing a director’s monthly compensation during the fiscal year can cause part of the compensation to become non-deductible for corporate tax purposes.
Hello, my name is Taisei Koshida, and I am a certified public accountant and licensed tax accountant in Japan. I assist foreign entrepreneurs and small businesses with accounting and tax matters in Japan, with support available in English.
Director compensation is treated differently from ordinary employee salaries under the Japanese corporate tax system. The amount and timing of changes matter for corporate tax purposes.
In this article, I explain when director compensation can be changed, what happens if it is increased or reduced during the director’s term of office, and the main exceptions to the general rule.
When Can Director Compensation Be Changed in Japan?
Under Japanese corporate tax rules, director compensation generally needs to satisfy certain requirements to be deductible as a company expense.
For regular monthly director compensation, the basic rule is that the monthly amount should remain the same. An ordinary annual revision is generally made within three months from the beginning of the fiscal year.
For a newly established company, this means that the director’s compensation should be determined within three months after incorporation.
This timing is important. After the amount has been determined, you cannot simply increase or decrease the director’s compensation later because the company is making more or less profit than expected and expect the entire amount to remain deductible for corporate tax purposes.
For more information about deciding the initial amount, see Director’s Compensation in Japan: A Key Step When Starting a Company.
Why Does the Three-Month Rule Matter?
In Japan, companies commonly determine or revise director compensation at a shareholders’ meeting near the beginning of the fiscal year.
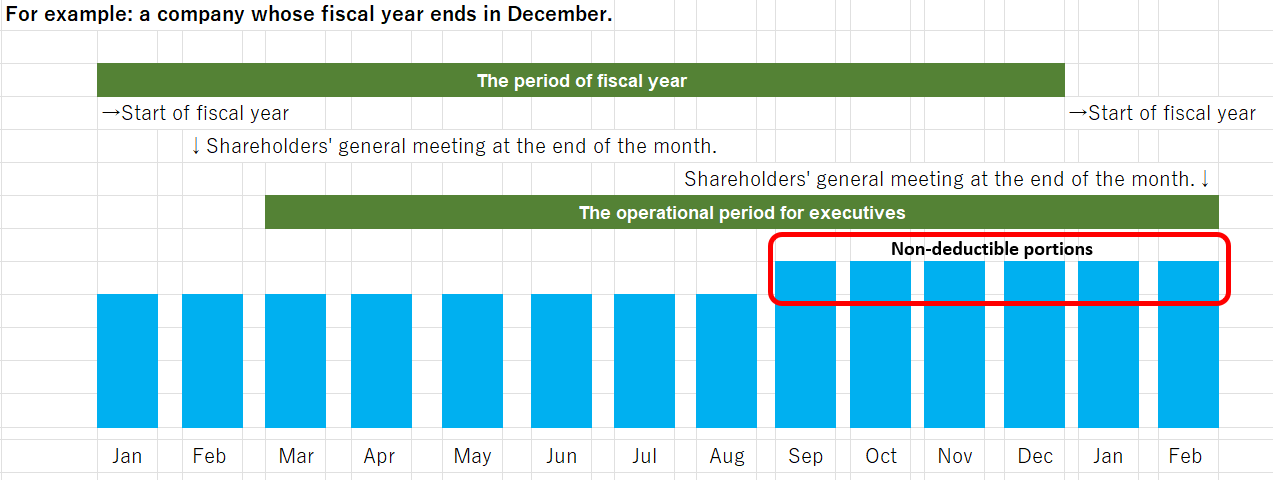
For example, suppose a company’s fiscal year ends in December and its shareholders’ meeting is held at the end of February. The new amount of director compensation can be determined at that meeting, and the director’s new term of office starts in March.
The three-month rule gives a company time near the beginning of the fiscal year to determine the compensation for the new period.
The important point is not that director compensation must always be changed in the third month. The important point is that an ordinary annual revision should generally be completed within the first three months of the fiscal year.
In small owner-managed companies, the president is often also the sole shareholder, so the formal process may be simple. However, the corporate tax rules concerning the timing and amount of director compensation still apply.
What Happens If Director Compensation Changes During the Director’s Term?
If director compensation is changed outside the permitted timing or without a qualifying reason, part of the compensation may become non-deductible for Japanese corporate tax purposes.
This does not mean that the company cannot pay the changed amount. The tax issue is whether the entire amount can be deducted when calculating the company’s taxable income.
The treatment is easier to understand with examples.
If Director Compensation Is Increased
For example, suppose a company whose fiscal year ends in December determines the director’s monthly compensation at JPY 500,000 at the shareholders’ meeting at the end of February.
The director’s new term of office starts in March, and the company pays JPY 500,000 per month from March through August.
If the company increases the monthly compensation to JPY 800,000 from September without a qualifying reason, the additional JPY 300,000 per month is treated as the non-deductible portion.
JPY 300,000 × 6 months from September through February = JPY 1,800,000
The chart below shows this treatment. The red box represents the increased portion that is not deductible.
This is why increasing director compensation later simply because the company has made more profit than expected does not work as an ordinary corporate tax reduction strategy in Japan.
If Director Compensation Is Reduced
The calculation works differently when director compensation is reduced.
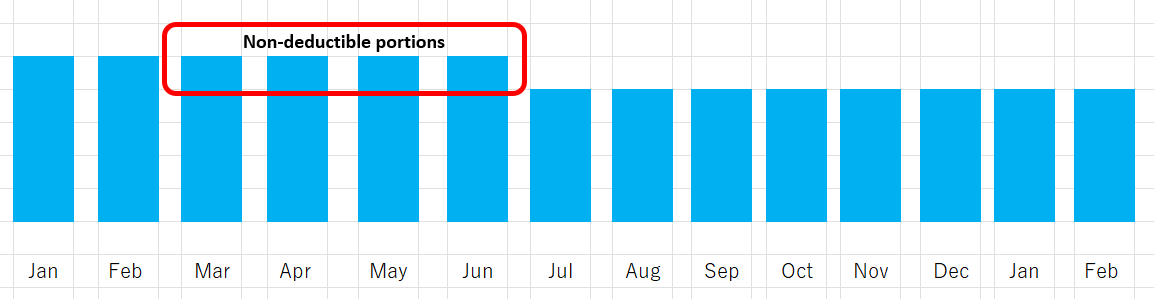
Suppose the director’s monthly compensation is JPY 800,000 from March through June and is reduced to JPY 500,000 from July without a qualifying reason.
In this case, the difference of JPY 300,000 for the four months from March through June is treated as the non-deductible portion.
JPY 300,000 × 4 months from March through June = JPY 1,200,000
The chart below shows this treatment. The red box represents the portion that is not deductible.
This is another reason why director compensation should not be changed casually during the director’s term of office.
Can Director Compensation Be Changed After Three Months?
Yes, in certain circumstances.
Japanese tax rules provide exceptions for certain changes caused by circumstances such as a significant change in a director’s position or responsibilities, or a serious deterioration in the company’s business performance.
However, these exceptions are limited. A company cannot freely change director compensation simply because profit is higher than expected, sales are lower than expected, or the company wants to reduce its tax bill.
In particular, a reduction caused by business deterioration requires more than simply saying that business has become a little worse. The actual circumstances of the company matter.
If you need to change director compensation after the first three months, I recommend checking whether the reason satisfies the Japanese corporate tax requirements before making the change.
Decide the Amount Carefully at the Beginning
Because director compensation cannot be changed freely during the fiscal year, the initial amount is important.
The company’s expected profit, cash flow, the director’s living expenses, individual income tax, corporate tax, and social insurance should be considered when determining the amount.
Setting the amount as high as possible to reduce corporate tax is not necessarily a good decision. Setting it unrealistically low to reduce individual income tax or social insurance can also create problems if the director actually needs substantially more money for living expenses.
For a newly established company, director compensation is also one of several tax decisions that need to be made soon after incorporation. The Blue Form application and consumption tax registration should also be reviewed early.
For an overview of these initial decisions, see Starting a Company in Japan: 3 Essential Tax Steps for Foreign Entrepreneurs.
For a broader guide to accounting in Japan, bookkeeping, payroll, consumption tax, corporate tax planning, and other issues for foreign business owners, see Starting & Running a Business in Japan: Tax and Accounting Guide for Foreign Business Owners.
Frequently Asked Questions
Can I Increase My Director Compensation If My Company Makes More Profit Than Expected?
The company can pay a higher amount, but increasing director compensation during the term simply because the company is more profitable than expected can cause the increased portion to become non-deductible for corporate tax purposes. The tax treatment should be checked before changing the amount.
Can I Reduce My Director Compensation If the Company Has Cash Flow Problems?
Possibly, but a reduction does not automatically qualify for tax purposes. A serious deterioration in business performance can qualify in certain circumstances, but a temporary decline in sales or a desire to reduce expenses is not automatically sufficient.
Does the Three-Month Rule Mean I Must Wait Three Months Before Setting Director Compensation?
No. A newly established company does not need to wait until the third month. The point is that the initial determination or an ordinary annual revision should generally be completed within the permitted three-month period.
Can a One-Person Company Change Director Compensation Whenever the Owner Wants?
No. In a one-person company, the director may also be the sole shareholder, so making a corporate decision can be simple. However, that does not remove the corporate tax requirements for deductible director compensation.
Should I Set Director Compensation as Low as Possible to Reduce Tax and Social Insurance?
Not necessarily. If the amount is too low for the director’s actual living expenses, additional withdrawals from the company can create accounting problems. Corporate tax, individual income tax, social insurance, company cash flow, and the director’s actual cash needs should be considered together.
Accounting and Tax Support for Foreign Business Owners in Japan
My main areas of expertise are accounting and taxation.
I assist foreign entrepreneurs and small businesses with accounting in Japan, corporate tax returns, director compensation, payroll-related tax matters, consumption tax, and corporate tax planning, with support available in English.
For director compensation, it is better to check the tax treatment before changing the amount rather than discovering the problem when preparing the corporate tax return.
When necessary, I also work with judicial scriveners for company registration, administrative scriveners for visa matters, social insurance specialists, and other professionals.